
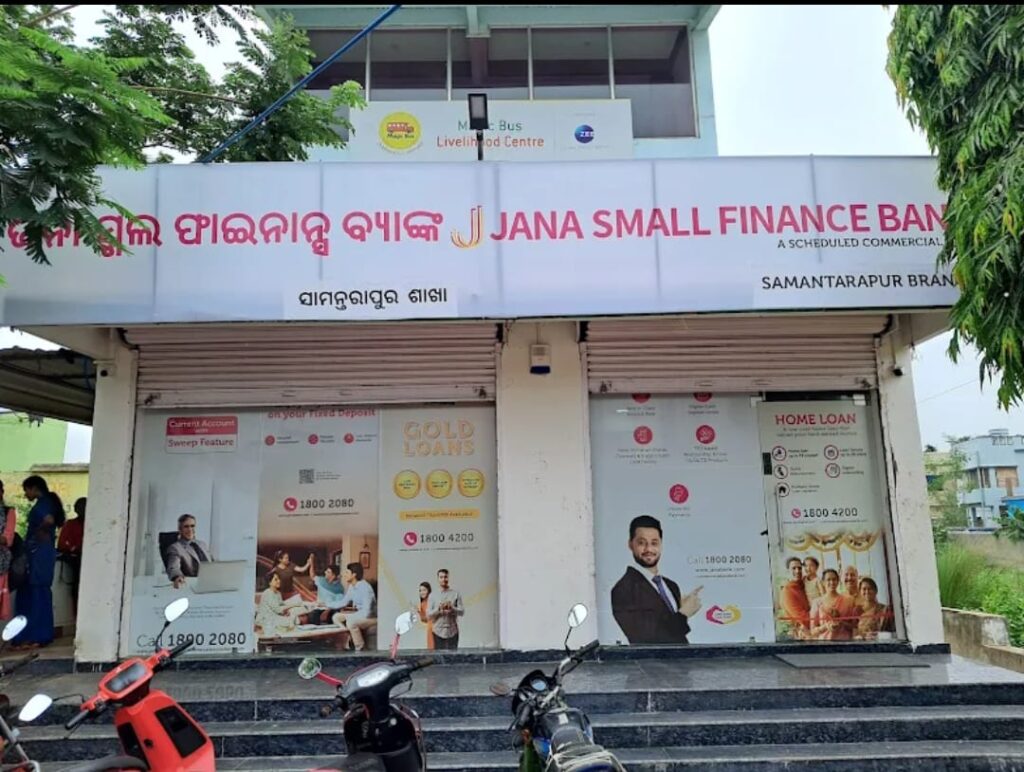
The Reserve Bank of India’s decision to return Jana Small Finance Bank’s application for universal banking status represents a significant milestone in the evolution of India’s small finance banking sector. On October 28, 2025, the Bengaluru-headquartered institution formally announced that its pursuit of full-fledged banking capabilities had been temporarily stalled due to unmet regulatory benchmarks.
Understanding the Application and Timeline
Jana Small Finance Bank submitted its transition proposal to the RBI on June 9, 2025, following the central bank’s April 2024 framework that established the pathway for small finance banks to upgrade to universal bank status. The institution had operated as a small finance bank since its establishment in 2018 and had crossed the mandatory five-year operational threshold that typically qualifies SFBs for such upgrades.
The regulator’s response, delivered late on October 27, 2025, did not elaborate on specific deficiencies, prompting the bank’s Managing Director and Chief Executive Officer Ajay Kanwal to characterize the development as a “return” rather than an outright rejection. This distinction carries significance—a return suggests the possibility of resubmission after addressing identified gaps, whereas a rejection would indicate fundamental unsuitability.
The Regulatory Framework and Jana’s Standing
For small finance banks seeking universal banking licenses, the RBI has established a comprehensive set of eligibility criteria. These include maintaining a minimum net worth of ₹1,000 crore, securing listed status on a recognized stock exchange, reporting consecutive years of profitability, and adhering to stringent asset quality metrics—specifically maintaining gross non-performing asset ratios below 3% and net NPA ratios under 1% for at least two financial years.
Jana SFB reported gross and net NPAs of 2.87% and 0.94% respectively in its September 2025 quarter, technically within the prescribed limits. However, the bank’s recent financial performance showed some volatility. Net profit declined sharply by 22.5% year-on-year to ₹74.9 crore in the second quarter of FY 2025-26, compared to ₹97 crore in the corresponding previous year period. This profitability compression may have triggered concerns about consistent earnings sustainability—a criterion the central bank views as fundamental for universal banking operations.
Market Reaction and Business Implications
The announcement immediately impacted Jana SFB’s equity valuation, with shares declining between 2.79% and 5.79% on the announcement day, reflecting investor disappointment about delayed expansion plans. The stock’s decline underscored market expectations that the upgrade would enhance the institution’s ability to diversify revenue streams and reduce the cost of funds—critical factors for competitive positioning against established universal banks.
Kanwal acknowledged that the inability to access universal banking status would postpone benefits from the liability side of operations. Specifically, he noted that securing universal bank status would have substantially reduced the bank’s funding costs, an advantage now deferred indefinitely. Conversely, from an asset perspective, Jana SFB’s operations remain largely unaffected, as the institution continues performing most activities permitted to universal banks, with the notable exception of co-lending arrangements.
The Competitive Landscape
Jana SFB’s regulatory setback arrives amid divergent outcomes for peer institutions pursuing similar transitions. AU Small Finance Bank, Jaipur-based and substantially larger than Jana, achieved the distinction of becoming the first SFB to secure RBI’s in-principle approval for universal banking conversion in August 2025. Ujjivan Small Finance Bank’s application, submitted earlier in February 2025, remained under review with expectations for a decision by December 2025.
The differential treatment among applicants highlights the RBI’s granular assessment approach, where each institution’s financial trajectory, governance framework, and operational excellence receive individualized evaluation rather than formulaic approval.
Strategic Path Forward
Jana’s management team outlined plans to engage directly with senior RBI officials to comprehend the specific concerns underlying the return decision. Kanwal indicated that once the deficiencies were identified and rectified, the bank would resubmit its application, though no timeline was provided. This approach—seeking regulatory feedback before reapplication—reflects a collaborative methodology that could prove more productive than proceeding through multiple rejections.
The institution’s underlying business fundamentals remain solid. With 4.6 million customers spread across 185 cities and over 3,300 employees, Jana SFB operates an extensive network focused on affordable housing loans that constitute approximately 73% of its loan portfolio. The bank’s priority sector lending stands at 90%, substantially exceeding the RBI-mandated 75% threshold, demonstrating commitment to financial inclusion objectives.
Broader Implications for the SFB Sector
Jana’s regulatory disappointment signals that the RBI maintains stringent standards for universal banking conversions. While the framework explicitly permits transitions, the central bank’s practical implementation reflects high scrutiny regarding financial stability, earnings consistency, and asset quality sustainability. This approach protects the banking system from premature or inappropriate upgrades while encouraging SFBs to strengthen operational excellence before pursuing transitions.
For Jana Small Finance Bank, the current setback need not signal permanent exclusion. The institution’s operational infrastructure, customer relationships, and market positioning remain intact. By systematically addressing the specific concerns flagged by RBI, the bank maintains a viable pathway toward eventual universal banking status, positioning itself for potential resubmission within the medium term.
The decision ultimately reflects the RBI’s continued emphasis on prudential banking standards, even as it gradually opens pathways for eligible institutions to expand their scope of operations.
- The 2026 Nationwide 3 Days Bank Strike: Why India’s Banking Backbone is Breaking
 Discover the root causes of the 2026 nationwide bank strike. Explore the struggle for 5-day banking, fair incentives, and why a Uniform Banking Standard is urgently needed to protect the dignity and job security of all bank employees.
- UPI MDR 2026: Is UPI Still Free? Here’s the Real Answer
 A simple guide to the new UPI MDR rules effective October 15, 2026 — who pays the 0.4% merchant charge, who doesn’t, and why UPI stays free for customers.
- Sole Proprietorship in India: Do You Need Registration? Documents & Benefits Explained
 Learn how to start a sole proprietorship firm in India, understand registration requirements, benefits, GST and Udyam registration, and discover the essential documents needed to open a business bank account. A simple beginner’s guide to launching your business confidently and correctly.
- What is HUF? The Ancient Rule Letting Modern Families Unlock Double Tax Benefits
 Want to legally save on income tax? Discover how a Hindu Undivided Family (HUF) protects wealth and maximizes tax benefits. Explore our complete guide on HUF eligibility, the 2005 amendment, and step-by-step instructions to open an HUF bank account.
- Exposed by RTI: Banks Recover 74% from Small Borrowers, Just 14% from Giants
 Shocking RTI data reveals a massive banking divide: banks recover 74% of bad loans from small borrowers but only 14.5% from corporate giants. Discover why ordinary citizens face harsh recovery agents while large defaulters enjoy massive loan write-offs.
- HDFC Bank Q3 Surprise: Profit Jumps 11.5% – Why Experts Call It a ‘Screaming Buy’ at ₹930
 HDFC Bank’s Q3 FY26 results shine: 11.5% profit surge to ₹18,653 Cr, GNPA at 1.24%, deposits up 11.5%. Beats estimates amid deposit wars—strong buy for 2026? Stock eyes ₹1,000 breakout.
- Withdraw PF Money in Seconds? EPFO’s New UPI Update is the Game-Changer
 Discover EPFO UPI withdrawal: Instant PF access in minutes via PhonePe or Google Pay. Step-by-step guide, eligibility, benefits, and tax rules for 2026. Skip delays—empower your savings today!
- The Truth Behind the “TCS Employee Salary Drop”: Viral News, Variable Pay and What It Means for You
 Discover the real reasons behind the viral TCS employee salary drop. From variable pay cuts to strict WFO mandates and performance bands, learn why IT take-home pay is shrinking and how to protect your earnings effectively.
- Stop! Don’t “Liquidate” Your ₹500 Notes Yet: What the New RBI Circular Actually Says
 GOI debunks viral ₹500 note discontinuation rumor. Fake news claimed RBI would ban notes by March 2026. Official clarification: ₹500 notes remain legal tender, ATMs continue dispensing them. Learn how to spot fake currency news and verify financial information.
- Cheques are Making a Huge Comeback in India—and They’re Now as Fast as UPI!
 India’s real-time cheque clearing system launched October 2025, processing cheques in hours instead of days. While Phase 2 was postponed, Phase 1 delivers same-day clearing with auto-approval features. Learn how continuous clearing speeds up banking for businesses and freelancers.
Your article helped me a lot, is there any more related content? Thanks!