
Boosting your credit score doesn’t have to feel like an uphill battle. With the right strategies and consistent effort, you can see measurable improvements in weeks not months. This interactive guide breaks down 10 easy actionable steps to help you elevate your credit score quickly, safely and sustainably. Along the way, you’ll find mini checklists, real-world examples and simple tips you can implement today.
Why Your Credit Score Matters
Your credit score is more than just a number—it’s your financial reputation. Lenders, landlords, insurers and even employers may check it. A higher score can unlock:
- Lower interest rates
- Better loan and credit-card approvals
- Higher credit limits
- Lower insurance premiums
Quick-Start Checklist
Before diving in, bookmark this mini checklist. It’ll help you track your progress:
- Pull your credit report
- Identify and dispute errors
- Pay bills on time
- Optimize credit utilization
- Automate payments
- Diversify account mix
- Use a secured credit card
- Keep old accounts open
- Limit hard inquiries
- Monitor regularly
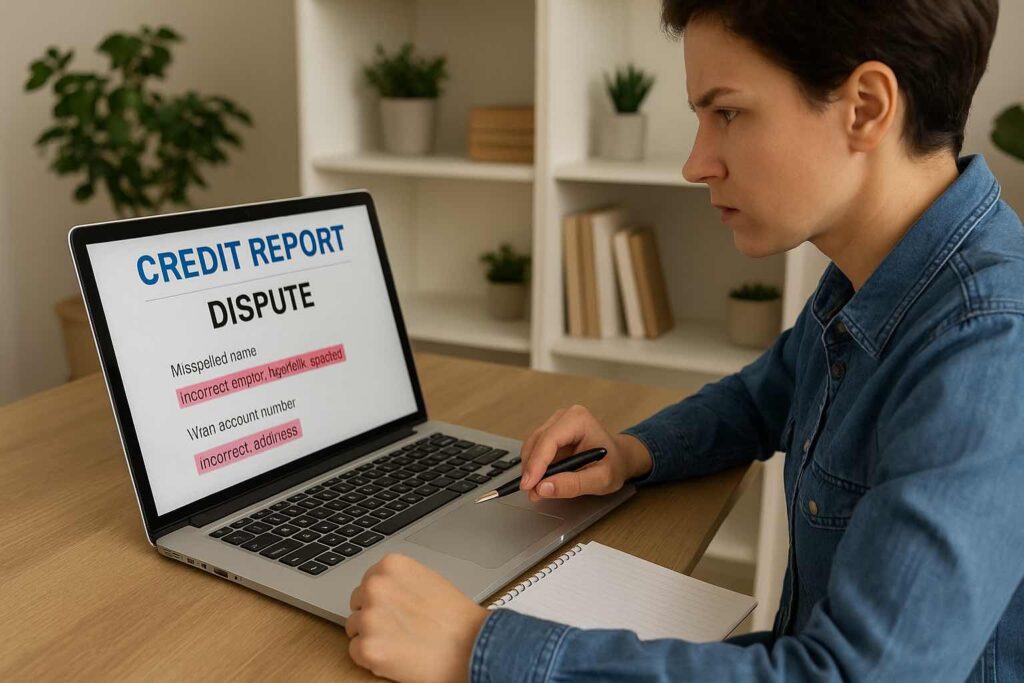
1. Pull and Review Your Credit Report
Why: Errors on your credit report can drag down your score.
How: Visit annualcreditreport.com (or your country’s equivalent) for a free copy.
Action: Check for incorrect personal details, duplicated accounts or false late payments.
Tip: Circle any discrepancies and file disputes online. Each corrected error can add 10–20 points to your score.
2. Dispute Mistakes Aggressively
Why: Fair Credit Reporting laws require credit bureaus to investigate disputes within 30 days.
How: Submit online disputes with documentation (bank statements, ID proof).
Action: Follow up with certified mail if needed.
Example: If a past-due mark is wrongly listed, a successful dispute could remove it and boost your score by 15–25 points.
3. Pay Every Bill On Time—Every Time
Why: Payment history accounts for ~35% of your FICO score.
How: Set calendar reminders or use auto-pay.
Action: Prioritize minimum payments on all credit cards and loans before the due date.
Interactive Tip: Try the “two-day rule”: Pay any bill at least two days before it’s due to buffer weekends and holidays.
4. Optimize Credit Utilization Ratio
Why: Utilization (balances vs. limits) drives ~30% of your score. Keeping it under 30% is key.
How: If you have a ₹50,000 limit, keep balances below ₹15,000.
Action: Spread spending across multiple cards or request a credit-limit increase.
Quick Formula: Utilisation% = (Total Balances/Total Limits)×100
Aim for 10–20% utilisation for fastest gains.
5. Automate Your Payments
Why: Eliminates forgetfulness and late fees.
How: Link bills to your bank account’s auto-debit or set up recurring transfers.
Action: Automate the minimum payment and manually top up the remainder for extra buffer.
Pro Tip: Schedule payments to auto-withdraw two days before due dates.
6. Diversify Your Credit Mix
Why: A healthy mix of installment loans (auto, personal) and revolving credit (cards) can boost your score (~10% weight).
How: Consider adding a small personal loan or secured credit card if you only have one type.
Action: Don’t open accounts you don’t need—only diversify mindfully.
7. Consider a Secured Credit Card
Why: Helps establish or rebuild credit when scores are low.
How: Deposit ₹5,000–₹10,000 as collateral; use the card like normal.
Action: Keep utilization low, pay on time and upgrade to an unsecured card after 6–12 months.
Real-Life Tip: Paying ₹500 monthly on a ₹10,000 secured card at 10% utilization and on-time payments can add 30+ points in six months.
8. Keep Old Accounts Open
Why: Credit-history length matters (~15% of score).
How: Resist the urge to close your oldest card, even if you don’t use it often.
Action: Make a small quarterly purchase to keep it active and avoid inactivity closures.
9. Limit Hard Inquiries
Why: Each hard inquiry can cost 5–10 points and stays on your report for two years.
How: Space out loan and credit applications by at least 6–12 months.
Action: Research prequalification offers to check rates without hard pulls.
10. Monitor Your Score and Adjust
Why: Ongoing monitoring helps you spot issues and measure progress.
How: Use free tools like Credit Karma or your bank’s score-tracker.
Action: Set monthly reminders to review your score and report changes.
Interactive Challenge: Track your score weekly for the first two months—identify which steps deliver the biggest boosts!
Bringing It All Together
By following these easy guides, you can make meaningful jumps in your credit score within 60–90 days. The key is consistency:
- Review & Correct your report
- Pay On Time and Automate
- Manage Utilization
- Build & Maintain healthy credit history
- Monitor and Optimize continuously
Implement these steps today to see your creditworthiness soar—and unlock better financial opportunities tomorrow!
- The 2026 Nationwide 3 Days Bank Strike: Why India’s Banking Backbone is Breaking
 Discover the root causes of the 2026 nationwide bank strike. Explore the struggle for 5-day banking, fair incentives, and why a Uniform Banking Standard is urgently needed to protect the dignity and job security of all bank employees.
- UPI MDR 2026: Is UPI Still Free? Here’s the Real Answer
 A simple guide to the new UPI MDR rules effective October 15, 2026 — who pays the 0.4% merchant charge, who doesn’t, and why UPI stays free for customers.
- Sole Proprietorship in India: Do You Need Registration? Documents & Benefits Explained
 Learn how to start a sole proprietorship firm in India, understand registration requirements, benefits, GST and Udyam registration, and discover the essential documents needed to open a business bank account. A simple beginner’s guide to launching your business confidently and correctly.
- What is HUF? The Ancient Rule Letting Modern Families Unlock Double Tax Benefits
 Want to legally save on income tax? Discover how a Hindu Undivided Family (HUF) protects wealth and maximizes tax benefits. Explore our complete guide on HUF eligibility, the 2005 amendment, and step-by-step instructions to open an HUF bank account.
- Exposed by RTI: Banks Recover 74% from Small Borrowers, Just 14% from Giants
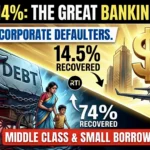 Shocking RTI data reveals a massive banking divide: banks recover 74% of bad loans from small borrowers but only 14.5% from corporate giants. Discover why ordinary citizens face harsh recovery agents while large defaulters enjoy massive loan write-offs.
Your article helped me a lot, is there any more related content? Thanks! https://bankermoney.com
Glad to hear from you! Please keep encouraging with your wonderful feedbacks and share it with your friends and family.
Can you be more specific about the content of your article? After reading it, I still have some doubts. Hope you can help me.
Thanks for sharing. I read many of your blog posts, cool, your blog is very good.
Pingback: Credit Utilization 30% Rule: Transform Your CIBIL Score
I don’t think the title of your article matches the content lol. Just kidding, mainly because I had some doubts after reading the article.